Key Highlights
An assignment of mortgage is the legal process that transfers a mortgage loan from the original lender to a new lender.
For Pennsylvania homeowners, the loan usually stays the same even after a mortgage assignment.
Your payment address or customer service contact information may change after the transfer.
These transfers often happen because of the sale of mortgage loans in the secondary mortgage market.
The assignment should be properly recorded to protect ownership rights and the chain of title.
You usually do not need to sign the assignment of mortgage.
Introduction
If you own a home in Pennsylvania, you may hear that your mortgage has been transferred and wonder what that means for you. A mortgage assignment is a common part of real estate lending, but it can still feel confusing. In simple terms, it means the lender’s rights under your loan move to another company. That change matters because it affects who handles your account, sends notices, and collects payments, even though your basic loan terms usually stay the same.
Understanding Mortgage Assignment in Pennsylvania
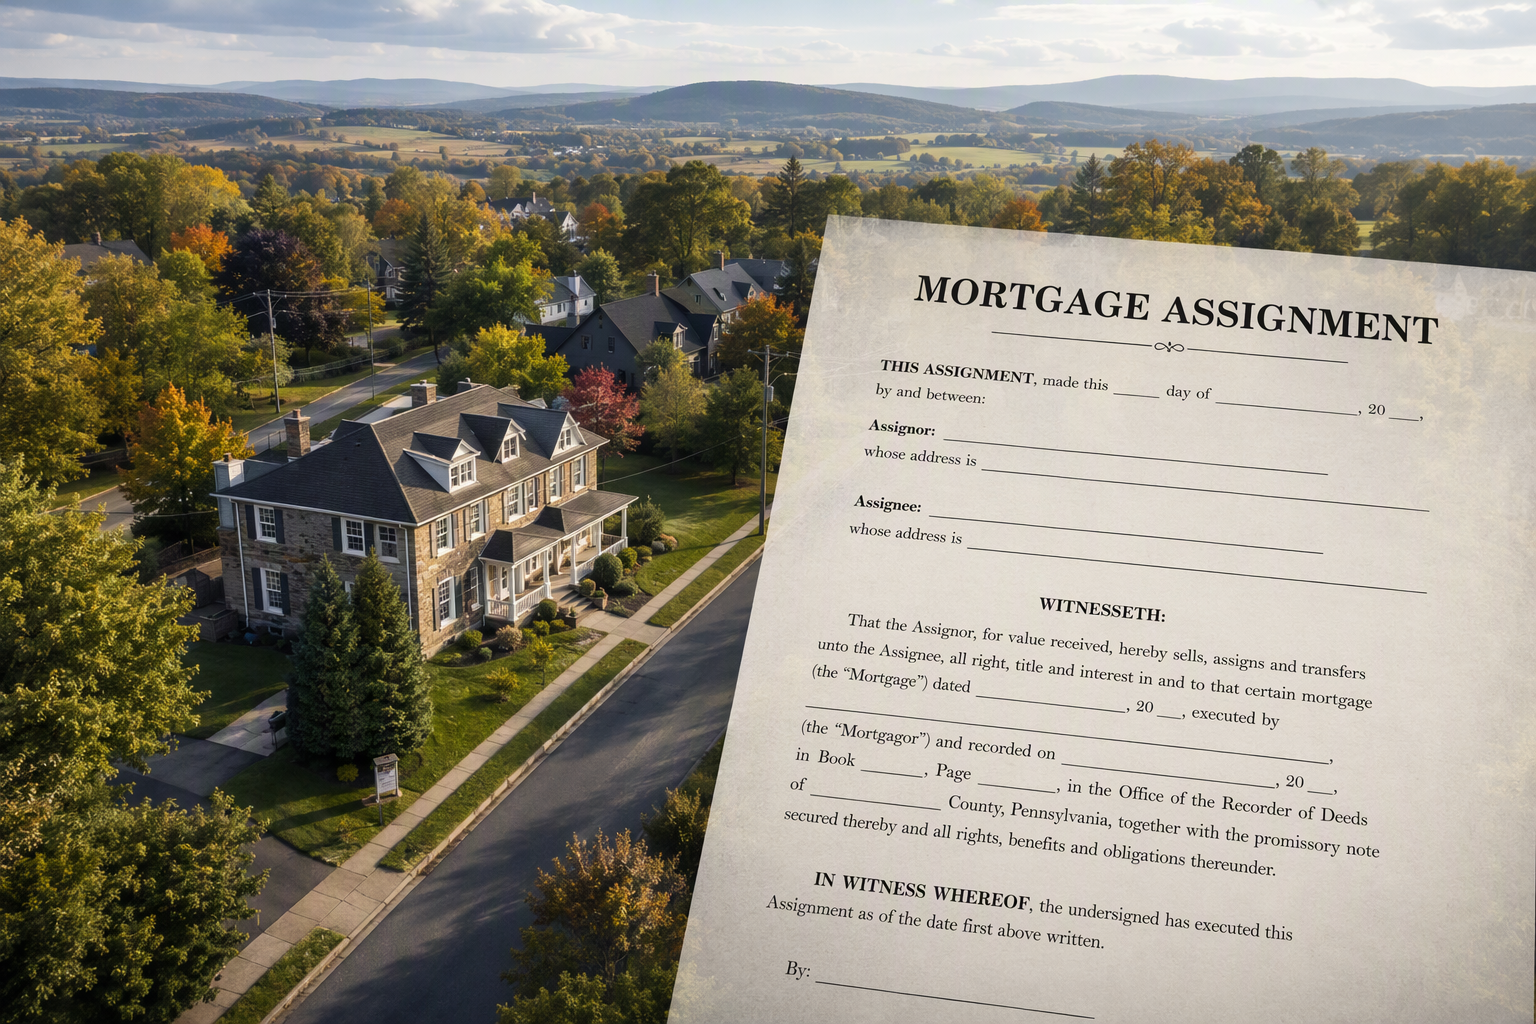
In Pennsylvania, an assignment of mortgage is a formal document used in real estate law to transfer a lender’s interest in a home loan. For a homeowner, this means the rights connected to the mortgage assignment move from one holder to another.
Put simply, under Pennsylvania law, your mortgage may be assigned without changing your role as the borrower. You still owe the debt, but a different company may hold the mortgage rights. That is why understanding the basics of mortgage assignment helps you know what to expect next.
What Is a Mortgage Assignment and How Does It Work?
A mortgage assignment is the transfer of a mortgage from one party to another through a formal document. In most cases, the original lender transfers its rights in the loan to a new lender or investor. This is often called the transfer of a mortgage.
Here is how the mortgage assignment usually works in Pennsylvania. The lender prepares an assignment of mortgage that shows the transfer. The borrower is typically notified, and the new lender takes over the rights connected to the mortgage. That can include collecting payments and enforcing the loan if default happens.
What does this mean for you? Usually, your loan terms do not change. The interest rate, amount of money owed, and payment obligations stay the same. The main difference is who owns the mortgage rights and where your payments go after the transfer.
Key Terms Homeowners Should Know
Before you read any transfer notice, it helps to know a few common terms. These words appear in legal forms and related legal documents, and they can make a mortgage assignment easier to follow.
Here are some key terms homeowners should know:
Promissory note: Your promise to repay the loan.
Assignment of mortgage: The document that transfers mortgage rights.
New lender: The company receiving those rights.
Mortgage payments: The amounts you continue to send as required.
Mortgage rights: The lender’s legal authority tied to the loan.
Deed of trust: A similar security document used in some states.
Knowing these terms can help you review notices with more confidence. It also makes it easier to ask the right questions about contact information, payment processing, and who now has the right to act on the loan.
Why Mortgages Are Assigned in PA
Many Pennsylvania homeowners are surprised when their mortgage loan moves to another company. In most cases, this happens because lenders regularly take part in the sale of mortgage loans after closing.
That activity is part of the secondary mortgage market. A lender may assign a mortgage to a different financial institution or investor, even though you still live in the same home and follow the same payment schedule. To see why this happens so often, it helps to look at the most common reasons.
Common Reasons for Mortgage Assignment
Mortgage assignments usually happen for business reasons, not because you did anything wrong. In real estate finance, lenders often move loans after closing as part of normal operations. That is why your mortgage may end up with a new lender.
Common reasons include:
The loan is transferred into the secondary market.
A bank sells mortgage rights to an investment firm.
A different company takes over payment processing or servicing.
Lenders reorganize their loan portfolios.
Mortgage rights are moved as part of broader real estate transactions.
Even when this happens, your loan terms usually stay in place. You still need to make payments on time, but you may need updated contact information and customer service details. Watching for a transfer notice helps you avoid sending mortgage payments to the wrong place.
The Difference Between an Assignment and a Loan Sale
These terms are related, but they are not always identical. The sale of mortgage loans often happens in the secondary mortgage market, while an assignment of mortgage is the formal step that transfers the lender’s rights in the recorded mortgage.
Think of it this way: a loan sale is the broader transaction, and the assignment is the document that helps carry it out. During or after real estate settlement, the loan may later be sold to a new owner, and the mortgage rights are then assigned to match that transfer.
For you as the borrower, both events can lead to a new company handling the loan. Still, the assignment is about legal rights tied to the mortgage itself. That distinction can matter during a title search, refinance, or foreclosure review.
Legal Process of Mortgage Assignment in Pennsylvania
A mortgage assignment is not just an internal business update. It is a legal process tied to real estate law, and proper paperwork matters. In Pennsylvania, the assignment should be handled as a formal transfer of the lender’s interest.
For homeowners, that matters because recording and notice help support clear ownership rights. If your mortgage assignment is made to another company, you should review any notice carefully, confirm the new contact information, and understand who now holds the mortgage rights under Pennsylvania law.
When and Where Is an Assignment Recorded?
In Pennsylvania, a mortgage assignment is generally recorded in the same county where the recorded mortgage is filed. This puts the transfer into the public record and helps preserve a clear chain of title. Recording is important because state laws can create disputes when transfers are not properly documented.
If you want to check an assignment, start with the local recorder of deeds office. That office maintains real estate records, including legal forms tied to mortgages and later assignments. A title search may also reveal whether the assignment was entered correctly.
The Role of MERS in the Assignment Process
You may see MERS named in mortgage paperwork. MERS stands for Mortgage Electronic Registration System, one of the electronic registration systems used in real estate lending. Its role is tied to tracking mortgage interests as loans move between lenders or investors.
In an assignment of mortgage, MERS can appear as the mortgage holder of record for administrative purposes. This can help streamline transfers by reducing repeated paper filings between parties. In practice, that means some changes in mortgage ownership are tracked through the system before a later recorded assignment appears.
For homeowners, the key issue is clarity. If MERS is involved, you still want to know who currently holds the mortgage rights and where to send payments. A clear chain of title and accurate public record remain important when questions come up about ownership or foreclosure processes.
Conclusion
In conclusion, understanding mortgage assignments is crucial for Pennsylvania homeowners navigating their financial landscape. As we've explored, a mortgage assignment can significantly impact your rights and responsibilities, making it essential to stay informed about the process. Whether you're selling your home or refinancing, knowing how these assignments work, including the role of MERS, can empower you to make well-informed decisions. If you have any further questions or need assistance with your mortgage situation, feel free to reach out for a free consultation. Taking charge of your mortgage knowledge can ultimately lead to greater peace of mind and better financial outcomes.
Frequently Asked Questions
Will a mortgage assignment affect my rights or responsibilities as a Pennsylvania homeowner?
A mortgage assignment usually does not change your main duties as the original borrower. You still must make payments under the same loan terms. What changes is who holds the mortgage rights. Notice requirements under the Real Estate Settlement Procedures Act and state laws help you know where to send payments.
Do I need to approve or sign anything for a mortgage assignment in Pennsylvania?
Usually, no. The assignment of mortgage is a formal document between lenders as part of the legal process. Under Pennsylvania law, the borrower typically does not need to approve or sign it. You should, however, receive a notice of an assignment of mortgage and review it carefully.
Can a mortgage assignment impact my home sale or refinance in Pennsylvania?
Yes, it can matter during a home sale or refinance if records are unclear. A title search may show the assignment of mortgage, and problems can arise if the transfer was not properly recorded. Clear real estate records help keep your transaction moving without avoidable delays.