Key Highlights
During the foreclosure process, property responsibility usually stays with homeowners until a foreclosure sale is completed and ownership fully changes.
In Michigan, even after a sheriff’s sale, homeowners often remain in the property during the redemption period.
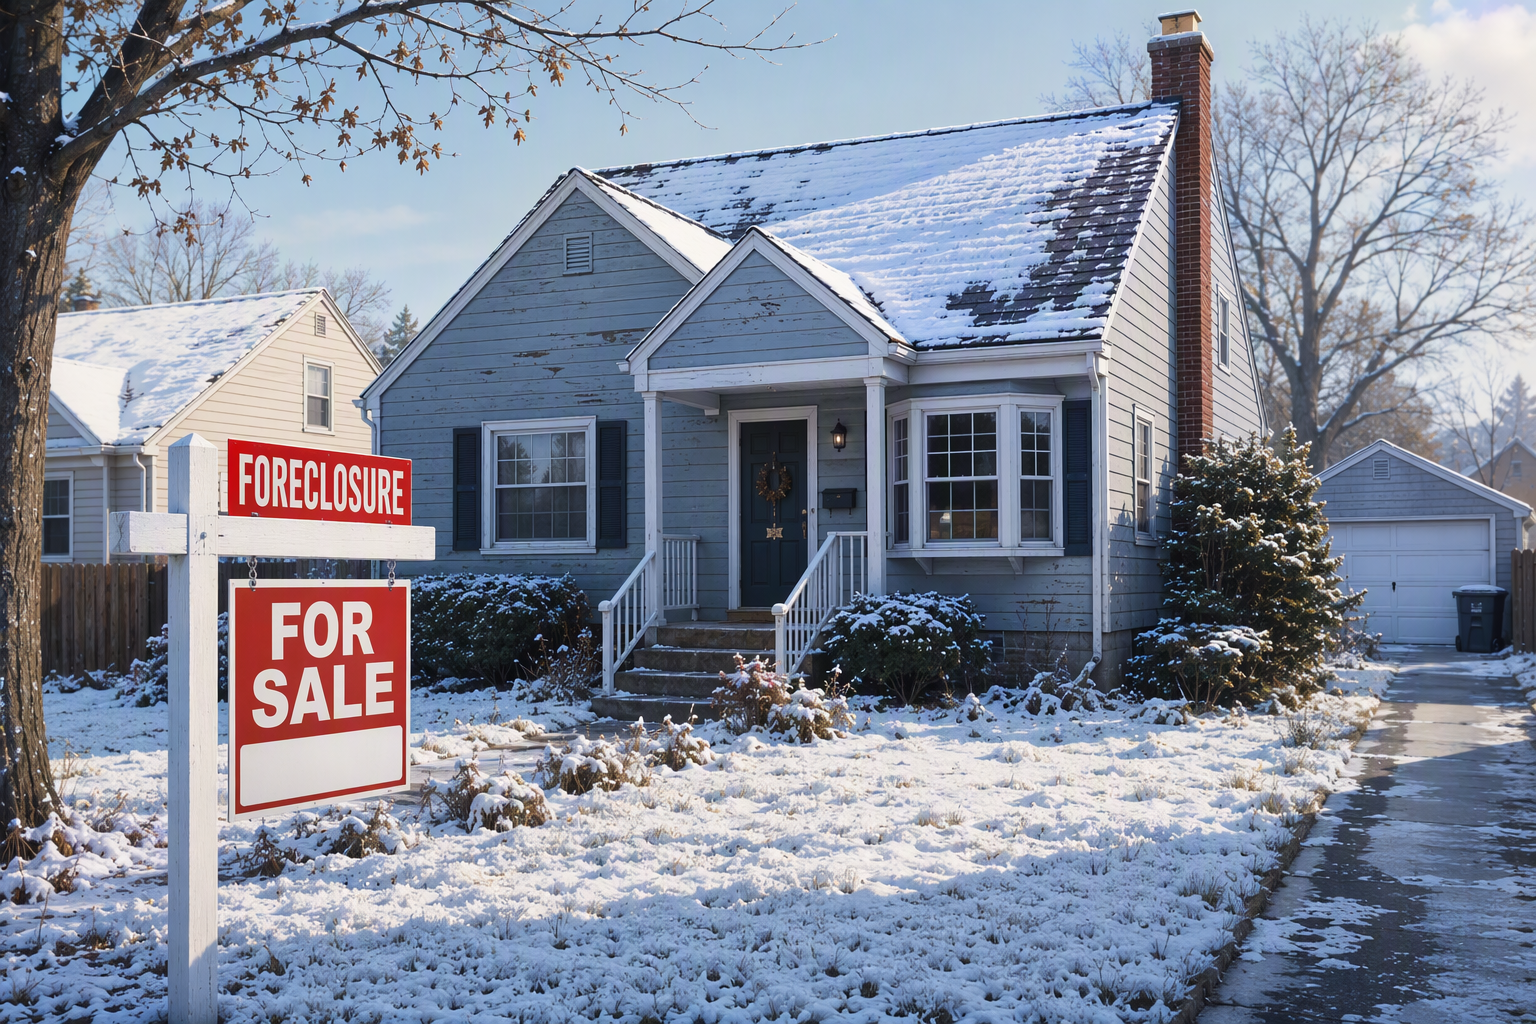
Winter damage can include snow, ice, frozen pipes, missing heat, or roof problems that threaten the home.
Banks or new owners may inspect the property, but control does not always shift right away.
Tenants keep important rights, and landlords still have maintenance duties before ownership changes.
Legal help and a housing counselor can help you understand state law and next steps.
Introduction
Winter damage can create serious problems when a home is already in foreclosure. You may be wondering who has to handle repairs after a storm, frozen pipes, or heavy snow. In real estate, that answer often depends on where the property is in the foreclosure sale timeline. Until ownership clearly changes, the person still holding ownership may remain responsible. The details can get confusing fast, especially when a lender, tenant, or new buyer is involved.
Understanding Foreclosure and Property Responsibility
To answer who is legally responsible for winter damage to a property during the foreclosure process, you first need to know who still controls the home. In Michigan, a homeowner usually keeps ownership during foreclosure proceedings until the legal process reaches a later stage.
That means legal responsibility for basic property maintenance often stays with the homeowner for a significant part of the foreclosure process. A new owner does not automatically step in the moment a notice appears. The timing of sale, possession, and transfer matters, which is why the next sections break down control and ownership.
The Foreclosure Process and Property Control
In Michigan, most foreclosure proceedings happen without a court order. The mortgage lender starts by advertising a foreclosure auction, often called a sheriff’s sale, if missed mortgage payments are not resolved. A notice of the sale is published in a local newspaper for consecutive weeks and posted on the property.
Even then, the foreclosure sale does not instantly remove the homeowner from the picture. Under state law, the homeowner still has options before the auction, such as loan modification, refinancing, selling the home, or catching up on the debt. Bankruptcy may also affect the legal process.
So who controls the property during this stage? In practical terms, the homeowner usually does. That is why legal responsibility for winter upkeep, including preventing avoidable damage, often remains with the owner until ownership truly shifts under the foreclosure laws.
Transition of Ownership During Foreclosure
The transition of ownership is not always immediate after a foreclosure sale. In Michigan, after a sheriff’s sale, there is usually a redemption period of about six months. During that amount of time, the former owner can stay in the home and try to redeem it by paying the sale price, fees, and interest.
Because the legal process is still unfolding, the new owner does not fully take ownership right away. The buyer may have inspection rights during the redemption period, but that is different from full possession and complete control over day-to-day conditions.
Yes, homeowners are still required to maintain the property during foreclosure, especially in winter, when they remain the owner or occupant. If damage is found and not fixed after notice, the buyer may start legal action, including an eviction process in some cases.
Winter Damage Explained in the Context of Foreclosure
Winter damage in foreclosure means harm caused by cold weather, snow, or ice while the property is moving through a mortgage default and sale process. These issues can make an already stressed situation much worse.
If a property suffers snow or ice damage while in foreclosure, the party who still has ownership or maintenance duties will usually be the one expected to address it. In many Michigan cases, that remains the homeowner until after the redemption period, not the mortgage lender. Next, it helps to look at the kinds of damage that trigger disputes.
Common Types of Winter Damage (Snow, Ice, Frozen Pipes, Roof Collapse)
Winter damage can show up in ways that quickly lower a home’s condition and value. During foreclosure, that matters because the buyer may inspect the home and raise concerns if the property is deteriorating or at risk of more damage.
Common problems include:
Heavy snow and ice that strain the structure or block safe access
Frozen pipes that can burst and damage walls, floors, or plumbing
Roof collapse or missing roof sections that expose the interior
Loss of heat that may lead to further property damage
Exterior neglect that creates safety or blight issues under local laws
If these problems happen while the homeowner still has legal responsibility, the homeowner may need to fix them. If the damage goes beyond normal wear and tear during the redemption period, the buyer may seek damages or move forward with other legal steps.
Impact of Seasonal Hazards on Properties Under Foreclosure
Seasonal hazards can change the condition of a property very quickly. Snow, ice, and extreme cold may worsen neglect, create safety concerns, or leave the home open to further damage. In a real estate setting, poor property condition can affect how the mortgage lender or buyer responds.
During the foreclosure process, the buyer at a sheriff’s sale may inspect the property during the redemption period. If the buyer believes damage exists or more damage is likely soon, they can give notice and demand that the issue be fixed within seven days.
How does winter damage affect the foreclosure timeline or proceedings? It may lead to added legal action, including an eviction case during the redemption period if the problem is not corrected. That can raise pressure, increase costs, and shorten the room you have to manage the situation.
Legal Responsibility for Property Maintenance During Foreclosure
Legal responsibility during a foreclosure action usually follows ownership and control. Under Michigan state law, the property owner often remains responsible for maintenance until the sale is final and the redemption period ends.
That point matters if winter damage appears before the title fully shifts. A bank may be the likely buyer, but that does not automatically make it responsible right away. To see how this works, it helps to separate the homeowner’s duty from the later shift to a lender or new owner.
Duty of Care for Homeowners While Foreclosure is in Progress
A homeowner does not lose all duties just because the foreclosure process has started. In Michigan, the owner can remain in the home during the redemption period and still has a role in property maintenance. That includes avoiding preventable damage and responding when serious issues appear.
The buyer has inspection rights after the sheriff’s sale, with notice requirements. If the homeowner unreasonably blocks an inspection, the buyer may begin legal action. If the buyer finds damage or believes damage is likely soon, the buyer can send notice and give seven days to fix the issue.
So are homeowners still required to maintain the property during foreclosure, especially in winter? In many cases, yes. If the owner fails to address damage beyond normal wear and tear, the buyer may seek eviction during the redemption period or sue for the loss.
Shift of Liability to Lenders or Banks After Sale/Redemption Period
Liability usually shifts after the foreclosure sale is completed and the redemption period ends. At that point, the new owner takes ownership of the property. If the mortgage lender was the buyer, the lender then steps in as the owner under the legal process.
Before that point, the lender may have limited rights, such as inspection, but not the full duty that comes with complete ownership. This is why timing matters so much when people ask whether the homeowner or bank pays for repairs after a winter event.
Can a bank hold a previous owner liable for winter damage that occurs during foreclosure? In Michigan, the buyer may sue if the former owner caused damage beyond normal wear and tear during the redemption period. State law and the facts of the damage will shape that claim.
Insurance Coverage for Winter Damage During Foreclosure
Insurance questions often come up fast when a frozen pipe bursts or snow damages a roof. During foreclosure proceedings, people often assume missed mortgage payments mean property insurance has already ended, but that is not always true.
Does homeowner’s insurance cover winter-related damage to a property under foreclosure? Coverage depends on whether the policy is still active and what the policy covers. The compiled guidance does not list exact claim rules, but ownership and timing still matter in real estate. The next sections explain when the homeowner’s policy may still matter and when a new policy may take over.
Does Homeowner’s Insurance Stay Effective in Foreclosure?
A foreclosure process does not automatically erase homeowner’s insurance the moment default begins. The owner may still be living in the property during the redemption period, and the mortgage loan relationship may still affect property coverage. That said, whether a claim is paid depends on the policy itself.
The compiled information focuses more on ownership and maintenance duties than on insurance claim details. It shows that the former owner may stay in the home for months after the sheriff’s sale. During that time, the owner still has a strong interest in keeping coverage active if possible.
So does homeowner’s insurance cover winter-related damage to a property under foreclosure? It may, if the policy remains effective and the loss falls within the policy terms. You should review the policy and contact the insurer quickly because foreclosure status alone does not answer the full question.
When Do Banks or New Owners’ Policies Take Over?
The transition of insurance usually follows the transition of ownership. After a foreclosure sale in Michigan, the buyer may still have to wait through the redemption period before becoming the full new owner. Until that point, insurance coverage questions can overlap with possession and control.
This means banks or a new owner’s policies generally take over after ownership fully changes, not just when the foreclosure sale happens. If you are unsure, confirm the exact transition date and ask for written contact information from the party claiming ownership.
Tenant Rights and Responsibilities in Foreclosed Properties Suffering Winter Damage
If you rent a home in foreclosure, your tenant rights do not disappear because your landlord fell behind. That is a key point. In Michigan, your rights and responsibilities generally stay the same during the foreclosure process.
Property responsibility also stays with the landlord until ownership changes after the redemption period. So if winter damage affects your rental, you should not assume the bank must fix it right away. The next sections cover what tenants should do, and what legal protections may apply during the eviction process.
Steps Tenants Should Take If Damage Occurs
If winter damage hits your rental property during foreclosure, act quickly and keep records. Tell your landlord about the problem right away. In Michigan, the landlord still owns the home and remains responsible for maintenance until the redemption period ends.
You should also protect yourself by documenting everything. Helpful steps include:
Take photographs of the winter damage and any unsafe conditions
Notify the landlord in writing and keep copies
Keep paying rent to the landlord until ownership actually changes
Seek legal help if repairs are ignored or conditions become serious
A housing counselor may also help you understand the foreclosure timeline, while a lawyer can explain tenant rights if the property is not kept in good repair. If the home changes ownership, ask for clear contact information so you know who is responsible next.
Legal Protections for Renters in Foreclosure Situations
Renters do have legal protections during foreclosure proceedings. Under Michigan state law, a foreclosure notice posted on the home is not an eviction notice. You still pay rent to your landlord while the landlord owns the property, and your basic tenant rights remain in place.
After the foreclosure is completed, many tenants are protected from immediate eviction. Some may get 90 days after the redemption period ends, while others may stay until the lease ends. That often depends on when the lease was signed and whether it is a legitimate lease.
Are there special protections for tenants if winter damage happens while their landlord’s property is in foreclosure? Yes, in the sense that the landlord’s maintenance duty continues until ownership changes, and tenants may seek legal help if either the old or new landlord fails to keep the home in good repair.
Addressing Repairs and Property Access During Foreclosure
Repairs during foreclosure often become a dispute about timing, ownership, and access. If snow or ice damage shows up, the first question is who still has the duty of maintenance under the foreclosure process.
Property access matters too. In Michigan, the buyer may inspect after the sheriff’s sale during the redemption period, but there are notice rules and limits. That means you cannot guess who pays for repairs just by looking at who bought the home at auction. The details below explain both payment and access.
Who Pays for Necessary Repairs Resulting from Winter Damage?
The answer usually depends on who owns the property when the damage happens. During foreclosure proceedings in Michigan, the former owner often remains in the home through the redemption period. That means responsibility for necessary repairs may still rest with that owner.
The lender or other buyer at the sheriff’s sale may inspect the property, but full responsibility does not always move at once. If the home is damaged and the issue is not corrected after notice, the buyer may take further steps, including eviction during the redemption period.
So if a property suffers snow or ice damage while in foreclosure, does the homeowner or the bank pay for repairs? In many Michigan cases, the homeowner pays while ownership is still with them. After the redemption period, the new owner or lender generally takes on that role.
Navigating Access to the Property for Inspection or Repair
Property access can be tense during foreclosure, especially when repairs are urgent. In Michigan, the buyer after the sheriff’s sale has the right to inspect the home during the redemption period. Before an inspection, the occupant should receive a notice with key details and at least 72 hours’ notice.
The inspection must happen at a reasonable time, and the buyer should try to work with the homeowner. The buyer may also look at the outside of the property as often as they want. After an inspection, the buyer can ask for information or photos about the condition of the home.
You cannot unreasonably deny property access for a lawful inspection. If you do, the buyer may begin an eviction process. For winter damage, this access can shape who verifies the problem, who demands maintenance, and how quickly the issue moves into legal action.
Preventing Winter Damage During Foreclosure
Prevention matters because winter damage can create extra legal and financial problems during foreclosure. If you are still the property owner, waiting too long can increase the risk of inspection disputes, repair demands, or even eviction action during the redemption period.
The compiled information does not give a winter checklist, but it clearly shows that maintenance duties continue while ownership remains with you. That makes early action important. The next two sections explain practical prevention steps for homeowners and how the bank’s role changes after occupancy or ownership shifts.
Practical Steps for Homeowners to Reduce Risks
If you are a homeowner in foreclosure, the safest approach is to stay engaged and not ignore the property. Prevention starts with understanding that your duties may continue through much of the foreclosure process, especially during the redemption period.
Focus on simple risk-reduction steps such as:
Respond quickly to notices about damage or inspection requests
Keep the home in compliance with local laws on property maintenance and safety
Preserve major systems and avoid stripped plumbing, wiring, or missing equipment
Document the property condition with photographs if problems arise
Contact your mortgage servicer, housing counselor, or legal help early
These steps matter because avoidable winter damage can lead to legal action. A homeowner who fixes a problem within the required time may avoid further trouble. Early communication can also open loss mitigation options like loan modification or other ways to reduce pressure.
Role of the Bank in Prevention After Occupancy Changes
The bank’s prevention role becomes stronger after a foreclosure sale matures into actual ownership. Before the redemption period ends, the bank or other buyer may inspect and monitor the property. Still, that is not always the same as taking over full property maintenance.
Once occupancy changes and the new owner takes title, prevention becomes part of the new owner’s job. At that stage, the bank or other new owner has more reason to secure the property, manage conditions, and reduce the chance of further damage.
For you, the key point is timing. If you are still in possession, do not assume the bank will step in just because a foreclosure sale happened. If the bank is the new owner after the redemption period, then prevention and upkeep are more likely to become its responsibility.
Consequences if Winter Damage Is Not Addressed
Ignoring winter damage during foreclosure can lead to bigger losses than the repair bill alone. Damage may lower property value, create safety issues, and increase conflict between the occupant and the buyer.
It can also affect the foreclosure timeline and lead to legal action. In Michigan, a buyer who sees damage or risk of damage may send notice and move toward eviction if the issue is not fixed. If the property becomes uninhabitable, the practical and legal problems can become much more serious.
Effects on Foreclosure Timeline and Costs
Winter damage can add cost and pressure at several points in the legal process. A damaged home may need urgent work, more inspections, or extra communication between the occupant and the buyer after the sheriff’s sale. That alone can make a hard situation harder to manage.
In Michigan, if the buyer finds damage or believes damage is likely soon, the buyer can issue notice and demand repairs within seven days. If the issue is not corrected, the buyer may file an eviction case during the redemption period. That can change the foreclosure timeline in a very real way.
So how does winter damage affect the foreclosure timeline or proceedings? It may speed up conflict, increase expenses, and trigger separate legal steps. Even if the foreclosure itself continues, the added costs and eviction risk can reduce your flexibility and options.
What Happens if a Property Becomes Uninhabitable?
If a property becomes uninhabitable during foreclosure, the compiled information does not set out a special winter rule. Still, it does show that serious damage can lead to faster disputes over possession, repairs, and compliance with maintenance duties.
For homeowners, the buyer may inspect, give notice, and start an eviction process during the redemption period if major damage is not fixed. For tenants, the old or new landlord may still have repair duties depending on where the legal process stands. In either case, the condition of the home can no longer be treated as a minor issue.
What happens if a foreclosed property becomes uninhabitable due to winter damage? Expect increased legal pressure, possible displacement concerns, and a stronger need for legal help. Once a new owner takes over, that party controls what happens next with occupancy and repairs.
Conclusion
In summary, understanding who is responsible for winter damage during foreclosure is crucial for both homeowners and tenants alike. Navigating the complexities of property maintenance and legal obligations can be daunting, especially when seasonal hazards pose a risk to unoccupied properties. By being informed about your rights and responsibilities, you can protect yourself from potential liabilities and ensure that necessary repairs are addressed promptly. It’s important to stay proactive in preventing damage, engaging with lenders, and understanding insurance coverage throughout the foreclosure process. If you have more questions or need personalized guidance, feel free to reach out for assistance.
Frequently Asked Questions
Can a previous homeowner be held liable for winter damage after foreclosure?
Yes, a previous homeowner may still face legal responsibility under state law if the damage happened during the redemption period or went beyond normal wear and tear after the foreclosure sale. Once the new owner fully takes title, later damage is usually handled under the new owner’s responsibility.
Does winter-related property damage delay the foreclosure process?
It can affect the timeline by creating extra inspections, repair demands, or legal action during the redemption period. The foreclosure process may continue, but winter damage can increase conflict, costs, and pressure, which may change how quickly related steps like eviction or compliance issues move forward.
Are tenants protected if their rental is damaged by winter conditions during foreclosure?
Yes. Tenant rights generally stay in place during foreclosure, and the landlord’s duty to maintain the home continues until ownership changes. Legal protections may also limit immediate eviction after foreclosure, so tenants should report winter damage quickly and seek legal help if repairs are ignored.